
In this guide
Define the three recordsUse a labelled exampleKeep units visibleReconcile through the actual actionCustomer money and provider credits measure different things. Combining them in one “balance” column makes an operational record difficult to interpret and can hide missing evidence. Use separate ledgers or clearly separated fields, joined by order and action references.
Define the three records
A customer-payment record describes money received for a defined order. A provider-purchase record describes money spent to acquire a credit package. A credit-movement record describes confirmed quantity changes from provider actions. The references can connect these records without pretending that one customer dollar is one provider credit.
Use a labelled example
In an illustrative business, a customer has paid a quoted amount while a provider recharge remains pending. The customer’s payment state can be confirmed even though no credit quantity has been applied. Conversely, a business may hold purchased credits before receiving a particular customer order. Neither condition proves the other record is wrong.
Keep units visible
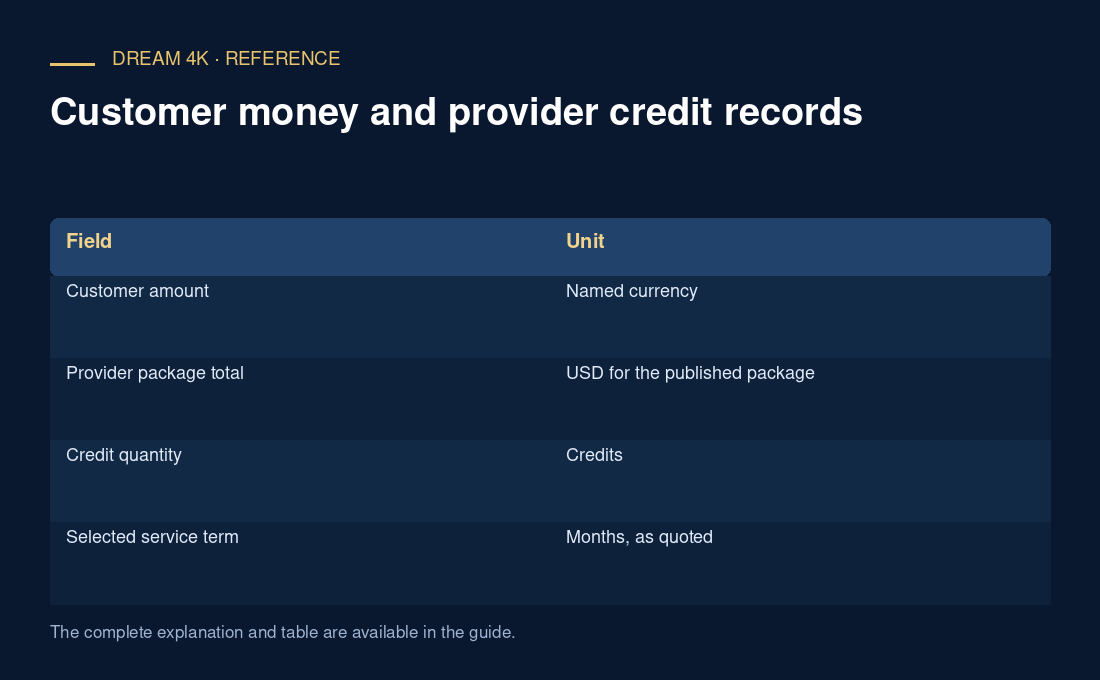
Use headings that name the unit and currency. Do not place subscription months in a credit-quantity field or use a customer’s local-currency payment to overwrite a USD supplier total.
| Field | Unit |
|---|---|
| Customer amount | Named currency |
| Provider package total | USD for the published package |
| Credit quantity | Credits |
| Selected service term | Months, as quoted |
| Action status | Text state with evidence reference |
Reconcile through the actual action
When the provider confirms the account operation, record its identifier and actual credit deduction if available. Link that operation to the customer order and the relevant provider purchase records. If consumption is unconfirmed, keep the allocation question open. This structure supports practical review without claiming a mandatory accounting method, guaranteed margin or universal credit conversion.
Questions about this guide
Can I calculate profit from the cash column alone?
No. Cash received does not establish the cost or completion of an order. You need the actual relevant costs, confirmed action and any other applicable expenses. This guide describes operational record structure and does not provide financial-reporting or profitability advice.